Tax in Monaco : Corinne Ricciardella in “The In House Lawyer”

Accueil - Publications - Tax in Monaco : Corinne Ricciardella in “The In House Lawyer”

The Principality of Monaco: a little-known attractive tax framework for the deployment of an international business activity

Monaco’s attractive tax system is commonly known for the total absence of income tax and wealth tax applicable to individuals residing in Monaco (other than French nationals), as well as the full exemption of gift and inheritance tax between spouses and in direct lines, giving rise to wealth planning opportunities for high-net-worth individuals.

Yet, the Principality of Monaco is also a destination of choice for the deployment of an international business activity by multinationals or foreign entrepreneurs.

Indeed, the Principality is an international onshore economic and financial centre that benefits from a central location within Europe, offering considerable operating advantages for the deployment of an international business activity on a day-to-day basis.

In addition to its ‘qualitative’ benefits, among which its sophisticated eco-system and rather low operating costs compared to London or other European economic hubs, the Principality provides for a stable and favourable business tax framework where corporate income tax applies only to certain business activities meeting a territorial criterion, including a five year progressive corporate income tax exemption for qualifying new businesses.

This article provides a high level overview of the main advantages offered by Monaco’s business tax framework.

A dynamic economic hub that meets international requirements for tax transparency and exchange of information

Although the Principality is neither a member state of the European Union nor the OECD, it offers the advantages of an independent state, while complying with the current international tax environment where transparency and exchange of information have become key.

Indeed, Monaco is a fully whitelisted jurisdiction for tax purposes per the Council of the European Union held on the 5 December 2017 where the Principality was withdrawn from any grey lists of non-cooperative states for tax purposes. The Convention on Mutual Administrative Assistance in Tax Matters developed by the Council of Europe and the OECD is fully applicable in Monaco and 35 tax information exchange agreements are currently into force.

Furthermore, the Principality is a participating country to the inclusive ‘BEPS’ framework (‘base erosion and profit shifting’) developed by the OECD, thereby committing to comply its tax legislation with OECD anti-abuse recommendations.

As a result of the above, Monaco generally does not fall under domestic tax anti-abuse mechanisms (CFC’s provisions, high taxation of transactions with blacklisted jurisdictions, etc) refraining multinationals and entrepreneurs from establishing a business in a tainted jurisdiction.

A stable and attractive business tax framework

Monaco does not provide for any direct tax on business profits other than corporate income tax (‘Impôt sur les bénéfices’) (‘CIT’) for certain business activities.

The scope of Monaco CIT is limited to commercial or industrial business activities which derive more than 25% of revenue outside of Monaco. Conversely, non-commercial business activity, such as strategic, intellectual or R&D consulting activities, are fully exempt from Monaco CIT.

In other words, CIT only applies when the two following cumulative criteria are met:

  • A qualitative criteria, pertaining to the nature of the business activity: CIT applies only to profits derived from business activities of a commercial (eg sale of goods) or industrial (eg production of raw materials) nature; and
  • A territorial criteria: CIT applies only if more than 25% of the revenue incurred upon the commercial or industrial activity is generated outside of Monaco. Conversely, if 75% of the revenue is generated in Monaco, no CIT applies (eg retail store activity).

By exception to the above criteria, CIT applies to companies whose business activity consists of earning revenue from patents, literary or artistic property rights.

When applicable, the rate of CIT is aligned with French CIT, ie its nominal rate is 25%.

However, rules governing the computation of the taxable basis are rather flexible, allowing in practice reducing significantly the effective tax rate.

In this regard, the cap mechanism applicable to the tax deduction of qualifying director fees is rather generous compared to that applicable in most EU jurisdictions.

This gives rise to relocation opportunities to Monaco for individual directors – although it is not compulsory for a Monaco joint stock company (‘Société Anonyme Monegasque’) to have Monaco-based directors: director fees are not taxable in the hands of the beneficiary directors in Monaco while allowing reducing the taxable basis of the Monaco paying entity – we also note that director fees do not bear any social charges and the possibility for individual directors of obtaining advantageous Monaco social security insurance under competitive conditions.

A number of corporate tax incentive regimes apply

Qualifying new businesses set up in Monaco can benefit from a progressive five-year tax exemption: a full CIT exemption applies during the first two fiscal years, then CIT is progressively applied, ie CIT is based on 25% of the tax profits of the third fiscal year, increased to 50% the fourth year and 75% the fifth year.

The incentive ‘headquarter’ tax regime makes the Principality of Monaco a preferred jurisdiction to locate foreign companies’ administrative offices. Indeed, qualifying headquarters, which, for the sole benefit of their group, carry out management, coordination or control tasks benefit from a reduced effective CIT rate of circa 2%, calculated on a flat-rate basis of their operating costs.

R&D tax incentives also apply: qualifying R&D businesses based in Monaco are supported through the benefit of R&D tax credits that can net off CIT due by the company, as the case may be.

Absence of ‘exit costs’

There is no ‘tax barrier’ to cross-border financial flows: no withholding tax applies in Monaco to dividend, interest or royalty paid by a Monaco-based entity to non-Monaco beneficiaries.

Besides, shareholders are not taxable on capital gains incurred upon the sale of shares in a Monaco company.
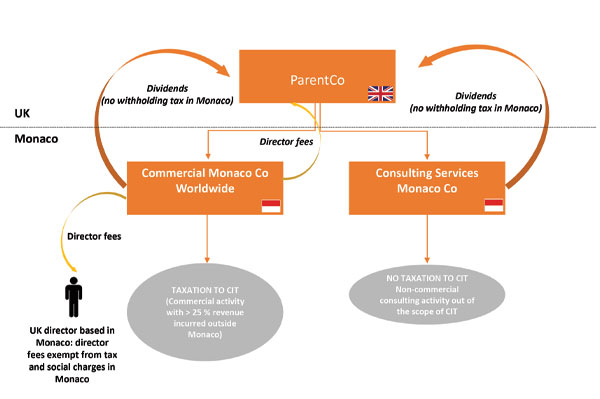
At a glance

  • At the level of the Monaco company subject to CIT: CIT tax base may be significantly reduced through the payment of director fees to Monacobased or foreign directors (whether individuals or companies)
  • At the level of the UK parent company:
      • No withholding tax will apply in Monaco on director fees and/or dividends paid by the Monaco company;
      • Dividend should be exempt under the parent-subsidiary tax regime;
      • Capital gains incurred upon the sale of share in the Monaco company will not be taxable in Monaco and should be exempt in the UK under the substantial shareholding exemption (SSE).

VAT – Monaco is part of the European Union VAT systemMonaco forms a customs union with France and is thus part of the European VAT system (Directive 2006/112/CE dated 28 November 2006 on the common system of value added tax ) – the Monaco standard VAT rate is 20%.

As a result of the above, in addition to multinationals expanding in Monaco, we note an increasing number of foreign entrepreneurs relocating to Monaco, thus benefiting from a full income tax exemption, and deploying their business from Monaco, either through consulting services rendered to their foreign-based business – with literally no risk of attracting any tax basis in Monaco based on a deem effective management of the foreign business from Monaco, or through the setting up of a new operating company in Monaco.

/

Our last news

Gordon S. Blair featured in the Global Law Experts & Global Advisory Experts Handbook 2026

Gordon S. Blair and its Managing Partner, Xavier de Sarrau, are featured in the 2026 edition of the Global Law Experts & Global Advisory Experts Handbook, published in September 2026, in the Monaco – Wealth Management Law section.   An international reference guide Published by Global Law Experts and Global Advisory Experts, the Handbook presents law and advisory firms around the world each year, organised by jurisdiction and practice area. It is aimed at business leaders and decision-makers seeking international advice.   More than a century advising on international wealth Founded in Monaco in 1920, Gordon S. Blair advises private individuals, entrepreneurial families, family offices, financial institutions and international groups on the structuring, protection and management of their private and corporate interests. Led by Xavier de Sarrau, a multidisciplinary team of around 50 legal and tax professionals advises on wealth management, international tax and estate planning, family governance, real estate, corporate law, M&A and cross-border projects.   Key expertise highlighted in the profile The profile published in the Handbook highlights several of the firm's areas of work: Relocation to Monaco: support at every stage of the process, from residency and international tax to wealth structuring, business establishment and regulatory matters. Wealth preservation and succession: trusts, foundations, family offices, holding structures and governance frameworks designed across generations and jurisdictions. High-value assets: yachts, aircraft, real estate and art collections, from acquisition to transmission, integrating legal, tax and regulatory advice.  
See more

Monaco strengthens the right to a bank account

Legal update – 16 October 2026 Published in the Journal de Monaco on 16 October 2026, Law No. 1.597 of 9 October 2026 strengthens the statutory right to a bank account introduced in 2020. The reform sets clearer deadlines for banks and facilitates access to the designation procedure where a bank refuses an application or fails to respond. Clearer processing deadlines The reform first sets a precise timetable for the bank receiving the application. Banks must request the necessary documents in writing within 30 working days of receiving a formally submitted application. Once all necessary documents have been received, the bank has 30 working days to open the account, subject to compliance with statutory due diligence requirements. A bank's silence constitutes an implied refusal One of the main advances of the law is the introduction of an implied refusal. Failure to respond within 30 working days of receiving the application, or following receipt of requested missing documents, constitutes an implied refusal. Eligible applicants may then refer the matter directly to the Budget and Treasury Department, without waiting for a refusal certificate. The Department must designate a bank within 10 working days of receiving the required documentation. Wider access to the right The law also removes two practical obstacles. First, eligible applicants may invoke their right to an account as soon as they receive notice terminating their existing account, without waiting for its actual closure. Second, holding a joint account does not prevent an eligible individual from opening an individual account. Remedies and sanctions The effectiveness of the regime is supported by judicial review and sanctions. A designated bank's refusal, or failure to open an account within the prescribed deadlines, may be challenged before the President of the Court of First Instance under the procedure applicable en la forme des référés. In addition, certain failures to issue a refusal certificate or to notify an applicant of a rejection may attract an administrative fine of up to €10,000. Best practice for applicants In practice, the reform highlights the importance of evidence. Applicants should formally submit their request by registered post, electronic registered delivery or hand delivery against a receipt, and retain evidence of the documents supplied. The right to an account remains subject to anti-money laundering and counter-terrorist financing requirements. Entry into force and transitional provisions The law took effect on 17 October 2026. Transitional provisions notably reserve the new application-processing rules and related sanctions for applications submitted after that date.
See more

Monaco: Draft Law no. 1131 introduces a new framework for crypto-asset services

Draft Law no. 1131 regulating the activities of crypto-asset service providers would introduce a new legal framework in the Principality. According to its explanatory memorandum, the proposed legislation notably reflects Monaco’s commitments under its Monetary Agreement with the European Union, including the adoption of measures equivalent to the European Markets in Crypto-Assets Regulation — MiCA. It also takes into account the recommendations of the Financial Action Task Force — FATF.   A deliberately limited opening The approach adopted by the Princely Government is based on strategic considerations relating to the international environment. It provides for a limited opening of the permitted services, notably to reduce the Principality’s exposure to the risks associated with certain crypto-asset activities. The selected services would therefore constitute a natural extension of financial activities already carried out in Monaco. Against this background, the draft law is largely aligned with amended Law no. 1.338 of 7 September 2007 on financial activities, while adapting certain provisions to the specific features of crypto-asset services, particularly in relation to operating requirements.   A framework limited to three services The draft law would authorise only three crypto-asset services: receiving and transmitting orders in crypto-assets on behalf of clients; • providing crypto-asset portfolio management services; • providing advice on crypto-assets. Other services falling within the scope of the proposed framework would be prohibited in the Principality. These would notably include: custody and administration of crypto-assets on behalf of clients; • operating a crypto-asset trading platform; • exchanging crypto-assets for funds; • exchanging crypto-assets for other crypto-assets; • executing orders on behalf of clients; • placing crypto-assets; • providing crypto-asset transfer services on behalf of clients. The issuance of crypto-assets within the Principality would also be prohibited. The draft law nevertheless provides for certain exclusions from its scope, notably for certain intragroup services, certain unique and non-fungible crypto-assets and crypto-assets already governed by other legal regimes.   Prior authorisation from the CCAF Providing any or all of the three permitted services would require prior authorisation from the Commission de Contrôle des Activités Financières — CCAF. Authorisation could be granted to: Monaco public limited companies meeting the conditions set out in the legislation; • credit institutions headquartered in a foreign State, operating through a branch in Monaco and already authorised by the CCAF under Law no. 1.338. Within their respective areas of competence, the CCAF would seek the opinion of the Autorité Monégasque de Sécurité Financière and the Agence Monégasque de Sécurité Numérique. It would issue its decision within six months of receiving a complete application. Authorisation would notably be subject to requirements concerning: financial guarantees, own funds and prudential safeguards; • the competence and good repute of directors and shareholders; • AML/CFT and asset-freezing obligations; • business continuity and operational resilience; • information systems security.   Client protection and conduct requirements Authorised providers would be subject to prudential and conduct-of-business rules, together with obligations relating to conflicts of interest, record-keeping and information systems security. Client mandates would have to be governed by written agreements. Providers would not be permitted to accept deposits of funds or crypto-assets from their clients. They would also be required to obtain information concerning each client’s knowledge and experience to assess whether the proposed service or crypto-asset is appropriate. Commercial approaches would also be regulated, particularly where made by unauthorised persons or entities. Restrictions would additionally apply to certain unsolicited approaches by authorised providers.   Supervision, penalties and market abuse The CCAF would be the competent authority responsible for supervising the implementation of the framework. Its powers would include: determining applications for authorisation; • monitoring compliance with professional obligations; • conducting inspections and investigations; • cooperating with foreign authorities; • implementing the measures and penalties provided for by the legislation. The draft law also provides for criminal penalties, notably where services are provided without authorisation or prohibited activities are carried out. A specific regime would additionally address market abuse involving crypto-assets, including the unlawful use or disclosure of inside information and market manipulation. Finally, the draft legislation would amend several Monaco laws relating to digital matters, financial activities and AML/CFT. Article 60 would notably repeal amended Law no. 1.491 of 23 June 2020 on token offerings and Title II of Law no. 1.528 of 7 July 2022.   A targeted approach Draft Law no. 1131 therefore adopts a targeted approach: only three crypto-asset services could be provided in the Principality, as an extension of existing financial activities and subject to prior CCAF authorisation. All other services falling within the proposed framework would be prohibited, together with any issuance of crypto-assets within Monaco. As the draft law remains subject to examination by the National Council, its provisions may evolve during the legislative process.
See more